Ventura County Real Estate • First-Time Buyer Guide 2026 • Last updated December 10, 2025

Ventura County First-Time Homebuyer Guide 2026: Rates, Dream For All, Down Payment Help & Local Strategy

Ventura County • First-Time Buyers • 2026 Market

Thinking about buying your first home in Ventura County in 2026? This guide walks you through mortgage rates, California down payment assistance (including the returning Dream For All program), and a step-by-step plan to go from "I'm curious" to getting keys in Ventura, Camarillo, Oxnard, Thousand Oaks, Simi Valley, and surrounding communities.

By Zac Wasserman, REALTOR® • Ventura & Los Angeles Counties • CA DRE #02210760

Ventura County first-time homebuyer mortgage and home loan illustration for 2026 buyers
✅ First-time buyer roadmap
📉 2026 mortgage rate outlook
🏡 Ventura County price examples
🎯 Dream For All prep checklist
Quick take: If you're a first-time buyer in Ventura County, 2026 is likely to be a year of stable-to-slightly-lower mortgage rates, tight but improving inventory, and powerful down payment tools like CalHFA's Dream For All returning. The buyers who win will be the ones who prepare early, understand their numbers, and lean on local guidance instead of headlines.

2026 Mortgage Rate Outlook for Ventura County First-Time Buyers

As we head into 2026, most major forecasters expect mortgage rates to hover in the mid-5% to low-6% range, rather than snapping back to the 3–4% world we saw in 2020–2021. That's important context for Ventura County buyers who are "waiting for rates to crash" before making a move.

What this means in practical terms:

  • Waiting for 3–4% again could mean waiting years — and potentially paying more for the same home if prices continue to edge up.
  • Buying at a payment you can afford now, and refinancing later if rates drop, is often a more realistic strategy.
  • In Ventura County, even a small bump in rates can move your monthly payment by hundreds of dollars, depending on price point.

Instead of chasing a perfect rate, focus on locking in the right home, in the right neighborhood, with a payment that fits your budget today. From there, you have options in the future. For deeper context on Ventura County pricing trends, check out the Ventura County Real Estate Market Update.

Why 2026 can still be a great year to buy

  • More sellers are adjusting to realistic pricing after the rapid run-ups.
  • Some buyers are still on the sidelines, which can mean less competition for you.
  • Programs like Dream For All and other down payment assistance can help close the gap.

How to protect yourself from payment shock

  • Ask your lender for scenarios at different rates (ex: 5.75%, 6.25%, 6.75%).
  • Explore seller credits and temporary rate buydowns.
  • Build a comfortable payment "ceiling" before you fall in love with a home.

How the 2026 Dream For All Program Works (and Why It Matters Here)

The California Dream For All Shared Appreciation Loan is scheduled to reopen in early 2026. It is designed to help first-time and first-generation homebuyers with a major boost to their down payment and closing costs.

High-level overview (subject to program updates):

  • Provides up to 20% of the purchase price (capped at a program maximum) for down payment and/or closing costs.
  • No monthly payments on this assistance; repayment happens when you sell, refinance, or transfer the home.
  • When you repay, you give back the original assistance amount plus a share of your home's appreciation.
  • To qualify, you must meet income limits, be a first-time buyer, and at least one borrower must meet the first-generation homebuyer definition.

In Ventura County, where home prices can make saving a full 20% down feel impossible, this program can be the difference between "I'll never be able to buy here" and "We closed on our first home."

How to prepare for the 2026 Dream For All lottery

Because space is limited and demand will be high, preparation is everything. Here is how Ventura County buyers can get ready before the registration window opens:

  1. Get fully pre-approved with a CalHFA-approved lender (not just pre-qualified).
  2. Confirm your eligibility as a first-time and first-generation buyer, including any documentation around your parents' housing history or foster care if applicable.
  3. Complete a homebuyer education course from a CalHFA-approved provider.
  4. Gather documents: pay stubs, W-2s or tax returns, bank statements, IDs, and any required forms.
  5. Meet with a local agent who understands Ventura County pricing and can help you target realistic neighborhoods once you receive a voucher.

Program guidelines can change. Always verify current guidelines directly with CalHFA and a licensed lender before making final decisions.

Other Down Payment Assistance Options for Ventura County Buyers

Even if you don't qualify for Dream For All, there are other programs that can make buying in Ventura County more attainable. These may include:

  • CalHFA first mortgage + MyHome assistance
  • Local city or county programs (which may be income-limited or targeted at certain professions)
  • Lender credits and grants partnered with major banks or credit unions
  • Employer-assisted housing benefits through large local employers or hospitals

Because each program has its own income limits, price caps, and property requirements, the smartest move is to sit down with both a local lender and a local agent who understand what's realistically available in Ventura, Camarillo, Oxnard, Thousand Oaks, Simi Valley, Moorpark, and surrounding areas.

Ventura County Market Snapshot: Prices, Inventory & Competition

Ventura County is a collection of very different micro-markets. Beach towns, hillside view homes, and more suburban neighborhoods all behave differently — but a few themes tend to hold true for first-time buyers:

  • Well-priced homes in move-in-ready condition still sell quickly, especially in entry-level price ranges.
  • Some sellers are adjusting expectations as days on market stretch in certain pockets, opening the door for negotiation.
  • Condition and location still drive demand — your strategy in Ventura might look different than in Camarillo, Oxnard, or Simi Valley.

In your price band, what matters most is not the county-wide average, but what similar homes are actually selling for in the neighborhoods you care about. That's where having fresh data and a local guide becomes critical. Stay informed with the latest trends in the Ventura County Real Estate Market Update.

How Much You Really Need to Buy in Ventura County

Every buyer's financial situation is different, but here is the framework I walk my first-time clients through when we're planning for a Ventura County purchase:

  1. Down payment – Anywhere from 3% down (for certain loan types) up to 20%+ if you're avoiding mortgage insurance or using Dream For All.
  2. Closing costs – Typically 2–3% of the purchase price, depending on loan type and rate structure.
  3. Reserves and safety cushion – I like buyers to have a post-closing cushion so they don't feel "house poor" on day one.
  4. Monthly payment comfort zone – What you're truly comfortable paying each month, not just what a lender will approve.

From there, we reverse-engineer your target price range and identify which Ventura County cities and neighborhoods align with that number.

Step-by-Step 2026 Ventura County First-Time Buyer Checklist

Here is a practical roadmap I use with first-time buyers across Ventura County:

  1. Clarify your "why" and time frame. Are you buying to stop renting, shorten your commute, build wealth, or get into a specific school boundary?
  2. Audit your finances. Review income, debts, savings, and credit with a lender who understands local programs.
  3. Get fully pre-approved, not just pre-qualified. A true pre-approval (with documentation) gives you stronger negotiating power.
  4. Explore down payment assistance. Check eligibility for Dream For All, CalHFA, local programs, and lender credits.
  5. Define your search criteria. Price ceiling, max monthly payment, must-have vs. nice-to-have features, and preferred cities.
  6. Tour the right homes, not every home. We'll focus on properties that match both your numbers and your lifestyle.
  7. Write a smart, data-driven offer. Based on recent comparable sales, seller motivation, and competition.
  8. Navigate inspections and appraisal. Understand what's normal, what's negotiable, and what's a deal-breaker.
  9. Close and move in with confidence. Final walkthrough, key handoff, and a plan for the first 90 days in your new home.
Want a personalized version of this checklist? Reach out and I'll send you a Ventura County–specific first-time buyer plan based on your price range, timeline, and preferred cities.

How to Compete (and Win) Without Being the Highest Offer

You don't always have to be the highest price to win an offer in Ventura County — especially as the market normalizes. Here are levers we can pull together:

  • Stronger terms (cleaner contingencies, realistic timelines, tight communication)
  • Seller credits (for closing costs or rate buydowns) instead of just more price
  • Flexible closing that matches the seller's needs (rent-back, shorter/longer escrow)
  • Local lender who can close on time and pick up the phone when the listing agent calls
  • Clear story about your strength as a buyer (employment, reserves, strong pre-approval)

First-Time Buyer Mistakes to Avoid in 2026

Some of the biggest mistakes I see first-time buyers make in Ventura County:

  • Shopping for homes before getting pre-approved – This leads to heartbreak and missed opportunities.
  • Chasing the "perfect" rate instead of focusing on a sustainable payment and the right home.
  • Ignoring total cost of ownership – Taxes, insurance, HOA, utilities, and maintenance all matter.
  • Trying to do everything alone – A good local team (agent + lender) can save you time, stress, and money.
  • Believing national headlines over local data – Ventura County is its own market, with its own trends.

Understanding these pitfalls early helps you avoid costly surprises. If you're concerned about wildfire risk and insurance availability, review the Ventura County Wildfire Risk & Home Insurance Guide.

Ventura County First-Time Buyer FAQ (2026)

How much do I really need for a down payment in Ventura County?

Many first-time buyers use programs that allow as little as 3–5% down, combined with closing cost credits or assistance programs. A full 20% down is great, but it's not the only path to buying a home here.

Is 2026 a bad time to buy my first home?

There is no universally "good" or "bad" year. For you, it comes down to your income, savings, stability, and how long you plan to stay in the home. If you can afford a comfortable payment, have reserves, and plan to hold the home for several years, 2026 can be a very reasonable time to buy.

Should I wait for mortgage rates to drop before I buy?

You can always refinance later if rates drop, but you can't go back and buy the same home at yesterday's price. For many Ventura County buyers, the smarter move is to buy at a sustainable payment now and improve the rate later if opportunities arise.

What if I don't qualify for Dream For All?

Dream For All is just one tool. You may still have access to other CalHFA programs, local assistance, lender credits, or strategies like seller-paid closing costs and rate buydowns. The right combination depends on your income, credit, and target price range.

How do I get started as a first-time buyer in Ventura County?

Start with a conversation. We'll look at your numbers, timeline, and preferred cities, then build a custom 2026 game plan for you — long before you start touring homes.


Zac Wasserman, Ventura County REALTOR® (CA DRE# 02210760)

About Zac Wasserman

REALTOR® | CA DRE #02210760 | RE/MAX ONE

I help buyers and homeowners navigate the Ventura County and Los Angeles County real estate market with practical, data-driven guidance—especially when rates, down payment programs, and neighborhood-level pricing affect affordability, timelines, and offer strategy.

Serving Ventura County · RE/MAX ONE | Westlake Village, CA

Ventura County Mortgage Rates October 2026: 7.4% and What Buyers Should Do

Ventura County Mortgage Rates October 2026 October 2026 Mortgage Market Update Ventura County Mortgage Rates October 2026: 7.4% and What Buyers Should Do Now If you have been watching Ventura County mortgage rates October 2026 headlines this month, you already know the news is not pleasant. The national 30-year fixed rate averaged 7.40% in the week ending October 8, which is the highest reading since late 2023. However, a higher rate does not automatically mean you should stop shopping for a home. Instead, it means you need a sharper plan. In this guide, I break down why rates jumped, what the Fed may do next, what the new rate does to your monthly payment, and five practical moves for buyers in Camarillo, Thousand Oaks, Oxnard, Simi Valley, and the rest of the county. Discuss Your Buying Options → Calculate Your Payment 30-Year Fixed 7.40% October 8, 2026 15-Year Fixed 6.73% National Average Year-Ago Average 6.30% October 2025 Source: Freddie Mac weekly mortgage survey. National averages are not personalized lending quotes. Ventura County Mortgage Rates October 2026: Where We Stand Let’s start with the numbers. According to Freddie Mac‘s weekly survey, the 30-year fixed-rate mortgage averaged 7.40% as of October 8, up from 7.28% the week before and well above the 6.30% average a year ago. Meanwhile, the 15-year fixed averaged 6.73%. As a result, borrowers who qualified comfortably in the summer are now running the numbers all over again. The recent climb has been steady rather than sudden. Rates sat near 6.7% in early September, then moved to 6.95% by September 17. Next, they crossed 7% on September 24 for the first time since January 2025, and they have kept rising since. Therefore, this is not a one-week blip, and buyers should treat it as the new starting point for planning. Important distinction: Freddie Mac’s survey measures a national average for conventional, conforming loans with 20% down and excellent credit. Consequently, your actual quote in Ventura County may be higher or lower depending on your credit score, down payment, loan type, and whether you need a jumbo loan. If you want the previous month’s snapshot for comparison, you can read my September 2026 Ventura County mortgage rate update. Why Mortgage Rates Jumped Above 7% Mortgage rates do not follow the Fed’s policy rate directly. Instead, they track longer-term borrowing costs, especially the 10-year Treasury yield. Therefore, anything that pushes inflation expectations higher tends to push mortgage rates up as well. Several forces have combined this fall. First, energy prices have stayed elevated during the ongoing conflict with Iran, and that has kept inflation worries alive. Second, the Federal Reserve raised its target range by 0.25 percentage points on September 16, to 3.75%–4.00%. That was the first hike since July 2023. Additionally, Fed officials signaled that another increase is likely before year-end. For a deeper look at that decision, see my breakdown of what the September Fed rate hike means for Ventura County and LA buyers. Why This Matters for Homebuyers In short, lenders are pricing in a world where inflation stays stubborn and rates stay higher for longer. Because of that, even good economic news can nudge mortgage rates upward. What the Fed Does Next: Dates to Watch Buyers who are tracking rates should circle three dates. First, September’s Consumer Price Index report arrives on October 14. Second, Freddie Mac releases its next weekly rate survey on October 15. Finally, the Fed announces its next policy decision on October 28. OCT 14 Inflation Report September CPI OCT 15 Freddie Mac Weekly Rate Survey OCT 28 Federal Reserve Policy Decision Markets currently expect the Fed to hold steady in October, with traders pricing only about a 20% to 25% chance of a hike at that meeting. However, many analysts still expect another increase in December. As a result, a hot inflation report could push mortgage rates higher before the October meeting, while a soft report could give them some relief. Nobody can time this perfectly, and that is exactly why I recommend building a plan that works at today’s rate instead of a hoped-for rate. You can follow the official schedule on the Federal Reserve’s FOMC calendar. What 7.4% Does to Your Monthly Payment Numbers make the impact easier to see. The table below shows the principal-and-interest payment on a 30-year fixed loan at three recent rate levels. I used 20% down on three example home prices of $750,000, $1,000,000, and $1,200,000, which produce loan amounts of $600,000, $800,000, and $960,000. These are illustrative examples, not Ventura County medians. Loan Amount At 6.30% A Year Ago At 6.69% Early August At 7.40% October 2026 Monthly Increase vs. A Year Ago $600,000 $3,714 $3,868 $4,154 +$440/month $800,000 $4,952 $5,157 $5,539 +$587/month $960,000 $5,942 $6,188 $6,647 +$705/month On smaller screens, swipe horizontally to view the complete table. Payments are rounded estimates for principal and interest only, assuming a 30-year fixed-rate loan. Payment Difference $587 More Per Month On an $800,000 loan, the estimated monthly principal-and-interest payment rises from $4,952 at 6.30% to $5,539 at 7.40%. Notice that these figures exclude property taxes, homeowners insurance, and any HOA dues. Moreover, insurance costs have risen across California, so your real monthly housing cost will be higher than the table shows. To see how this changes your own budget, try the Ventura County mortgage calculator or read my guide on how much house you can afford in Ventura County. Ventura County Homebuyers Wondering What You Can Actually Afford? Higher mortgage rates don’t have to leave you guessing. Let’s discuss your budget, target neighborhoods, and opportunities to negotiate better purchase terms in Ventura County. Let’s Build Your Buying Strategy → Zac Wasserman | REALTOR® | RE/MAX ONE 5 Smart Moves for Ventura County Buyers Right Now Higher rates change the strategy, but they do not end the opportunity. Here is what I suggest. MOVE 01 Get Fully Pre-Approved and Compare Multiple Lenders Rate quotes can vary meaningfully from one lender to the next. Therefore, request at
Read More »

Should You Sell Now or Wait Until Spring? Ventura County Fall/Winter 2026 Guide

Ventura County Home Seller Guide | Fall / Winter 2026 Should You Sell Now or Wait Until Spring? Ventura County Fall/Winter 2026 Guide By Zac Wasserman, REALTOR® (CA DRE# 02210760), RE/MAX ONE | Updated October 9, 2026 If you own a home in Ventura County and you’ve been thinking about listing, you’re probably asking one question: should you sell now or wait until spring? It’s a fair question, because the market changed this fall. Mortgage rates climbed to 7.40% in early October. The Federal Reserve raised rates for the first time since 2023, and the holidays are only a few weeks away. However, the local numbers tell a more useful story than the headlines do. In this guide, I’ll walk through what September’s MLS data shows and what each choice is likely to cost you. I’ll also explain how to decide based on your own situation. Should You Sell Now or Wait Until Spring? The Short Answer For most Ventura County homeowners, selling this fall makes sense if you need to move within the next six months. It also makes sense if you’re buying another home in the same market or if your home is ready to show today. On the other hand, waiting makes sense if your home needs work and your timeline is flexible. You should also be able to carry the home comfortably through winter. Therefore, the right answer depends less on the calendar and more on your price, your preparation, and your next move. Free Home Valuation → One thing is clear from the data, though: timing matters far less than pricing. In September, homes that were priced correctly sold in a median of 20 days at full price. Meanwhile, homes that needed a price reduction took a median of 70 days. As a result, a well-priced November listing can outperform an overpriced April listing. What the Ventura County Market Looks Like Heading Into Winter I pulled every closed sale in the county for September, and the full breakdown is in my September 2026 Ventura County market update. Here are the numbers that matter most for sellers: Closed sales: 489, compared with 497 in August Median sale price: $875,000 across all property types, and $950,000 for single-family homes Median days on market: 31 Median sale-to-list price ratio: 98.6%, down slightly from 99% in August Sellers who reduced their price before selling: 32% Sellers who paid a credit toward the buyer’s closing costs: 39%, with a median credit of $7,750 In other words, the market is steady but no longer forgiving. Prices are holding, and homes are still selling in about a month. However, roughly one in three sellers had to cut their price. In addition, nearly four in ten paid part of the buyer’s costs. Furthermore, most of those September closings went under contract in August, before rates jumped. Consequently, I expect the October and November data to show somewhat longer market times and more negotiation. How 7.40% Mortgage Rates Change the Math for Sellers According to Freddie Mac’s Primary Mortgage Market Survey, the average 30-year fixed rate reached 7.40% on October 8, 2026. That is up from 7.28% a week earlier and 6.30% a year ago. In addition, the September Fed rate hike lifted the federal funds range to 3.75%–4.00%, and several Fed officials have signaled that one more increase is possible before year-end. You can check upcoming meeting dates on the Federal Reserve’s FOMC calendar. So what does that mean for your buyer? For example, consider someone purchasing the county’s median-priced home at $875,000 with 20% down. At 6.30%, the principal and interest payment on a $700,000 loan is about $4,333 a month. At 7.40%, that same payment is about $4,847. Therefore, today’s buyer pays roughly $514 more every month than a buyer did a year ago for the same house. Because of that, buyers are more payment-sensitive than they were last spring. They negotiate harder, they ask for credits, and they walk away from homes that feel overpriced. Still, the buyers who are shopping right now are serious, because nobody tours homes at 7.40% for fun. Many of them have a job relocation, a lease ending, or a home they’ve already sold. It’s also worth being honest about what nobody knows. Rates could ease by next year if inflation cools. Alternatively, they could move higher if the Fed raises again. For that reason, waiting for a better rate environment is a bet, not a plan. The Case for Selling Now First, you’ll typically face less competition. Many homeowners delay listing once the holidays approach. As a result, the buyers who are still looking have fewer homes to choose from. A clean, well-priced home stands out. Second, you stop the clock on carrying costs. Every month you wait, you keep paying the mortgage, property taxes, insurance, and maintenance. For example, those costs might total $5,000 a month on your home. If so, waiting from November to April costs about $25,000 before you ever accept an offer. Your number will differ, so run it with your own bills. Third, if you’re also buying, the same conditions work in your favor on the purchase. In September, 39% of sellers paid a buyer credit and 32% cut their price. As a result, you’ll likely have room to negotiate on your next home. In fact, selling and buying in the same market often cancels out much of the timing risk. Finally, you avoid the uncertainty. Today’s prices are known: the county median is $875,000. In addition, well-priced homes are selling at full price in about three weeks. Next year’s prices and rates, however, are only a forecast. If you’re worried about where things are headed, I covered the longer outlook in my post on a possible housing market crash in 2027. The Case for Waiting Until Spring Waiting is a perfectly reasonable choice for some sellers, and I’d rather tell you that than push you to list. First, the spring market usually brings more buyers. Families often

Read More »

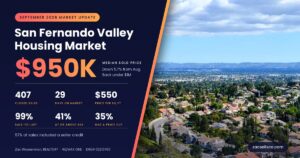
San Fernando Valley Housing Market Update: September 2026 Prices, Trends & City-by-City Data

SEPTEMBER 2026 · MARKET UPDATE San Fernando Valley Housing Market Update: September 2026 Prices, Trends & City-by-City Data The median slipped under $1 million, but single-family prices moved just 1.1%. Here is what actually changed. Get My Free Home Valuation By Zac Wasserman, REALTOR® (CA DRE# 02210760), RE/MAX ONE. Published October 7, 2026. Based on 407 closed residential sales recorded in the MLS for September 1–30, 2026. The San Fernando Valley housing market crossed a line in September that people will notice: the median sold price slipped back under $1 million. However, the headline hides more than it reveals. Single-family prices barely moved, condo and townhome prices actually rose, and the real change is happening at the top of the market and in how long homes sit. Below, I break down what closed, what it sold for, and what it means for your next move. In this update:At a Glance|Median Price|Days on Market|Prices by City|Condos & Townhomes|Mortgage Rates|For Sellers|For Buyers|FAQ San Fernando Valley Housing Market at a Glance: September 2026 The median sold price in the San Fernando Valley was $950,000 in September 2026, based on 407 closed sales. Homes took a median of 29 days to sell and closed at roughly 99% of their final list price. Here are the Valley-wide numbers for the month: Closed sales: 407 (down from 446 in August) Median sold price, all homes: $950,000 (down from $1,007,500) Median price per square foot: $550 Median days on market: 29 (August: 28) Median sale-to-list ratio: 99% Sold at or above asking: 41% (August: 44%) Sold after at least one price cut: 35% Sales with a seller concession: 57% In short, fewer homes closed, the middle price came down, and buyers negotiated on more than half of all deals. Even so, speed held steady, which tells me demand is still there for homes that are priced correctly. For a side-by-side look, you can compare these figures with August's San Fernando Valley numbers. San Fernando Valley Median Home Price: Why It Slipped Below $1 Million A 5.7% one-month drop in the median sounds dramatic. However, it does not mean your home lost 5.7% of its value in thirty days, and here is why. First, look at single-family homes on their own. The median single-family sale was $1,170,000 in September, compared with $1,182,500 in August. That is a 1.1% move, which is ordinary month-to-month noise. Similarly, the median price per square foot for houses eased from $609 to $597. Second, look at what closed. Three of the Valley's most expensive communities posted much lower medians than the month before, because a different mix of homes sold there: Encino: $1,525,000 (August: $2,050,000) Studio City: $1,474,500 (August: $1,900,500) Calabasas: $1,550,000 (August: $1,911,500) As a result, the Valley-wide median was pulled down by fewer high-end closings in those areas, while most mid-priced neighborhoods held flat or rose. In other words, this was a mix shift far more than a price cut across the board. That said, the luxury tier still closed deals. Forty-six homes sold for $2 million or more, and nine closed above $5 million, led by a $12,000,000 sale in Encino. Meanwhile, 54% of all September sales closed under $1 million, which is where most of the buyer activity lives right now. How Fast Are Homes Selling? Days on Market and Price Cuts Speed is where this market splits in two. Overall, the median home sold in 29 days. However, that single number blends two very different experiences. On one hand, 27% of homes went under contract within two weeks. On the other hand, another 27% sat for more than 60 days. Therefore, a seller's outcome depends heavily on which group the home lands in, and pricing is what decides it. The data makes this point clearly. Homes that sold without a price reduction took a median of 19 days. Homes that needed a reduction took a median of 67 days, and the typical cut was about $50,000, or 5.6% of the original asking price. Consequently, overpricing by 5% cost those sellers roughly seven extra weeks and usually the same money in the end. Concessions matter too. In 57% of September sales, the seller contributed toward the buyer's costs, with a median credit of $26,000, or about 2.5% of the sale price. Because of that, the true net for many sellers is lower than the recorded sale price suggests. For example, a home that closed at "99% of list" with a 2.5% credit effectively sold closer to 96.5%. Finally, attached homes moved more slowly than houses. Single-family homes sold in a median of about 27 days, while condos took 38 days and townhomes took 47. San Fernando Valley Home Prices by City The table below covers every Valley community with at least eight closed sales in September. Smaller samples can swing sharply from month to month, so treat cities with fewer than 20 sales as directional. San Fernando Valley home prices by city, September 2026 City Sales Median Sold Price Median $/Sq Ft Median Days on Market Sale-to-List Sold After a Price Cut Calabasas 17 $1,550,000 $590 45 98% 47% Encino 50 $1,525,000 $628 24 98% 32% Studio City 24 $1,474,500 $676 25 97% 17% Sherman Oaks 43 $1,399,000 $683 29 98% 30% Tarzana 12 $1,337,500 $523 29 97% 25% Woodland Hills 59 $1,175,000 $572 27 98% 32% West Hills 29 $1,070,000 $516 23 99% 31% Lake Balboa 8 $902,000 $482 21 100% 25% Northridge 25 $875,000 $495 36 100% 60% Chatsworth 24 $856,000 $452 43 99% 50% North Hollywood 31 $845,000 $564 32 99% 58% Winnetka 18 $827,500 $441 34 99% 33% Reseda 14 $826,500 $505 28 100% 36% Canoga Park 17 $815,000 $504 36 99% 24% Van Nuys 24 $811,000 $490 47 100% 17% Panorama City 10 $730,000 $477 22 102% 30% A few patterns stand out. The entry-level Valley is the competitive Valley. Panorama City sold at a median of 102% of list, and 80% of its sales closed at or above asking. Likewise, about 85%

Read More »