
Ventura County Mortgage Rates October 2026: 7.4% and What Buyers Should Do Now
If you have been watching Ventura County mortgage rates October 2026 headlines this month, you already know the news is not pleasant. The national 30-year fixed rate averaged 7.40% in the week ending October 8, which is the highest reading since late 2023. However, a higher rate does not automatically mean you should stop shopping for a home. Instead, it means you need a sharper plan. In this guide, I break down why rates jumped, what the Fed may do next, what the new rate does to your monthly payment, and five practical moves for buyers in Camarillo, Thousand Oaks, Oxnard, Simi Valley, and the rest of the county.
Source: Freddie Mac weekly mortgage survey. National averages are not personalized lending quotes.
Ventura County Mortgage Rates October 2026: Where We Stand
Let's start with the numbers. According to Freddie Mac's weekly survey, the 30-year fixed-rate mortgage averaged 7.40% as of October 8, up from 7.28% the week before and well above the 6.30% average a year ago. Meanwhile, the 15-year fixed averaged 6.73%. As a result, borrowers who qualified comfortably in the summer are now running the numbers all over again.
The recent climb has been steady rather than sudden. Rates sat near 6.7% in early September, then moved to 6.95% by September 17. Next, they crossed 7% on September 24 for the first time since January 2025, and they have kept rising since. Therefore, this is not a one-week blip, and buyers should treat it as the new starting point for planning.
Important distinction: Freddie Mac's survey measures a national average for conventional, conforming loans with 20% down and excellent credit. Consequently, your actual quote in Ventura County may be higher or lower depending on your credit score, down payment, loan type, and whether you need a jumbo loan.
If you want the previous month's snapshot for comparison, you can read my September 2026 Ventura County mortgage rate update.
Why Mortgage Rates Jumped Above 7%
Mortgage rates do not follow the Fed's policy rate directly. Instead, they track longer-term borrowing costs, especially the 10-year Treasury yield. Therefore, anything that pushes inflation expectations higher tends to push mortgage rates up as well.
Several forces have combined this fall. First, energy prices have stayed elevated during the ongoing conflict with Iran, and that has kept inflation worries alive. Second, the Federal Reserve raised its target range by 0.25 percentage points on September 16, to 3.75%–4.00%. That was the first hike since July 2023. Additionally, Fed officials signaled that another increase is likely before year-end.
For a deeper look at that decision, see my breakdown of what the September Fed rate hike means for Ventura County and LA buyers.
Why This Matters for Homebuyers
In short, lenders are pricing in a world where inflation stays stubborn and rates stay higher for longer. Because of that, even good economic news can nudge mortgage rates upward.
What the Fed Does Next: Dates to Watch
Buyers who are tracking rates should circle three dates. First, September's Consumer Price Index report arrives on October 14. Second, Freddie Mac releases its next weekly rate survey on October 15. Finally, the Fed announces its next policy decision on October 28.
Markets currently expect the Fed to hold steady in October, with traders pricing only about a 20% to 25% chance of a hike at that meeting. However, many analysts still expect another increase in December. As a result, a hot inflation report could push mortgage rates higher before the October meeting, while a soft report could give them some relief.
Nobody can time this perfectly, and that is exactly why I recommend building a plan that works at today's rate instead of a hoped-for rate. You can follow the official schedule on the Federal Reserve's FOMC calendar.
What 7.4% Does to Your Monthly Payment
Numbers make the impact easier to see. The table below shows the principal-and-interest payment on a 30-year fixed loan at three recent rate levels. I used 20% down on three example home prices of $750,000, $1,000,000, and $1,200,000, which produce loan amounts of $600,000, $800,000, and $960,000. These are illustrative examples, not Ventura County medians.
| Loan Amount |
At 6.30% A Year Ago |
At 6.69% Early August |
At 7.40% October 2026 |
Monthly Increase vs. A Year Ago |
|---|---|---|---|---|
| $600,000 | $3,714 | $3,868 | $4,154 | +$440/month |
| $800,000 | $4,952 | $5,157 | $5,539 | +$587/month |
| $960,000 | $5,942 | $6,188 | $6,647 | +$705/month |
On smaller screens, swipe horizontally to view the complete table. Payments are rounded estimates for principal and interest only, assuming a 30-year fixed-rate loan.
On an $800,000 loan, the estimated monthly principal-and-interest payment rises from $4,952 at 6.30% to $5,539 at 7.40%.
Notice that these figures exclude property taxes, homeowners insurance, and any HOA dues. Moreover, insurance costs have risen across California, so your real monthly housing cost will be higher than the table shows.
To see how this changes your own budget, try the Ventura County mortgage calculator or read my guide on how much house you can afford in Ventura County.
Higher mortgage rates don't have to leave you guessing. Let's discuss your budget, target neighborhoods, and opportunities to negotiate better purchase terms in Ventura County.
Let's Build Your Buying Strategy →Zac Wasserman | REALTOR® | RE/MAX ONE
5 Smart Moves for Ventura County Buyers Right Now
Higher rates change the strategy, but they do not end the opportunity. Here is what I suggest.
Get Fully Pre-Approved and Compare Multiple Lenders
Rate quotes can vary meaningfully from one lender to the next. Therefore, request at least three written quotes on the same day and compare both the rate and the closing costs. Freddie Mac itself notes that shopping around can save borrowers thousands over the life of a loan.
Ask About a Rate Lock With a Float-Down Option
If you are in contract, a lock protects you if rates keep climbing. In addition, a float-down feature lets you capture a lower rate if the market improves before closing. Not every lender offers it, so ask early.
Negotiate the Price and the Terms, Not Just the Rate
When payments jump, many buyers pull back, and sellers often respond with more flexibility. For example, you can ask for a price reduction, a seller credit toward closing costs, or funds for a temporary rate buydown. A credit that lowers your payment in the first one or two years can be worth real money.
Strengthen Your Credit Before You Apply
Even a modest improvement in your score can lower your rate. If you are not sure where you stand, my guide on what credit score you need to buy a home in Ventura County walks through the tiers.
Plan to Refinance if Rates Fall
If you buy today and rates drop later, you can often refinance into a lower rate. You cannot refinance a home you never bought, and you cannot renegotiate the price after you close. For that reason, many buyers focus on getting the right home at the right price and treat the rate as something that can change later. However, refinancing is never guaranteed, so make sure the payment works for you today.
Should You Wait for Lower Ventura County Mortgage Rates?
This is the question I hear most, and the honest answer is that it depends on your situation. On the one hand, waiting could pay off if inflation cools and rates retreat. On the other hand, nobody knows when that will happen, and the Fed has already signaled that more hikes may be coming.
Furthermore, waiting carries its own costs. If rates fall, more buyers will return to the market at the same time, and that competition can lift prices and erase some of your savings. Meanwhile, you keep paying rent while you wait.
Three Questions to Ask Before Buying
If you can answer yes to all three, waiting for a perfect rate may cost you more than it saves. If the answer to any of them is no, then patience, saving a larger down payment, or improving your credit may be the smarter path.
For a broader view of where prices may head, take a look at my analysis on whether the housing market will crash in 2027.
What Higher Rates Mean for Ventura County Sellers
Higher rates affect sellers too. Because buyers' payments are higher, fewer buyers can qualify at any given price, and the pool of motivated buyers gets smaller. Therefore, pricing realistically from day one matters more than ever. Homes that are priced well and presented well still attract offers, while overpriced listings tend to sit.
If you are a homeowner weighing your options, I wrote a separate guide on whether to sell now or wait until spring in Ventura County. In addition, you can request a free home valuation to see what your home might sell for in today's market.
Higher mortgage rates can influence buyer demand, pricing, and your selling strategy. Get a better understanding of your home's potential market value before deciding on your next move.
Request Your Free Home Valuation →Local insight for Ventura County and surrounding communities.
Frequently Asked Questions
What are mortgage rates in Ventura County right now?
Freddie Mac reported a national 30-year fixed average of 7.40% for the week ending October 8, 2026. Local quotes in Ventura County vary based on credit score, down payment, loan size, and loan type, so request personalized quotes from several lenders.
Why are mortgage rates going up in October 2026?
Rates have risen because of persistent inflation concerns, elevated energy prices, and the Federal Reserve's September rate hike. Mortgage rates follow longer-term Treasury yields more closely than the Fed's policy rate, so inflation expectations matter a great deal.
Will mortgage rates go down before the end of 2026?
No one can say for certain. Markets currently expect the Fed to hold in October and possibly raise rates again in December, which suggests rates may stay elevated. A softer inflation reading could bring some relief, however.
Should I buy a home now or wait for rates to drop?
If you can afford the payment today, plan to stay for several years, and find the right home, buying now and refinancing later if rates fall is a common strategy. If the payment feels stretched, waiting while you build savings and credit may make more sense.
How much more does a 7.40% rate cost per month than a year ago?
On an $800,000 loan, moving from 6.30% to 7.40% adds about $587 per month in principal and interest. The exact change depends on your loan amount and your final rate.
Can I refinance later if I buy at 7%?
Often yes, provided rates drop, your credit stays strong, and you have enough equity. Refinancing involves closing costs, so you should run the numbers before deciding.
Ready to Make a Move Despite Higher Rates?
Whether you are buying your first home or moving up, the right strategy can make Ventura County mortgage rates October 2026 feel a lot more manageable. Ready to talk through your options? Contact Zac Wasserman at RE/MAX ONE, your local Ventura County expert, through the contact page, and let's build a plan that fits your budget and your timeline.
Zac Wasserman is a licensed REALTOR® (CA DRE# 02210760) with RE/MAX ONE, serving homebuyers and sellers throughout Ventura County and surrounding communities. His local real estate coverage focuses on housing market conditions, property values, mortgage trends, and practical buying and selling strategies.
CA DRE# 02210760 | ZacSellsCA.com | Contact
Zac Wasserman is a licensed REALTOR® (CA DRE# 02210760) with RE/MAX ONE. Mortgage rate figures are national averages reported by Freddie Mac and are provided for information only. This article is not financial or lending advice, so please consult a licensed mortgage professional for a personalized quote.
- All Posts
- Buyer Guides
- California Home Insurance & Wildfire Risk
- Home Financing (Mortgage & Loan Guides)
- Market Updates & Forecasts
- Seller Guides
- Back
- Ventura County Real Estate Market Updates
- San Fernando Valley Real Estate Market Updates (Monthly): Prices, Inventory & Trends
Ventura County Mortgage Rates October 2026 October 2026 Mortgage Market Update Ventura County Mortgage Rates October 2026: 7.4% and What...
Ventura County Home Seller Guide | Fall / Winter 2026 Should You Sell Now or Wait Until Spring? Ventura County...
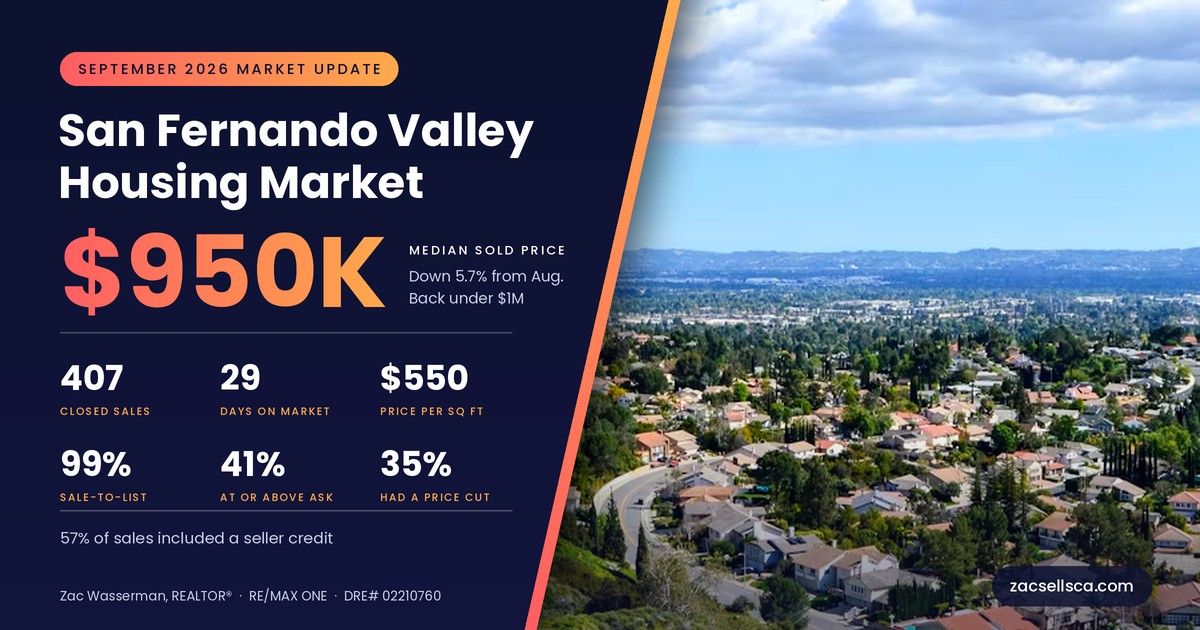
SEPTEMBER 2026 · MARKET UPDATE San Fernando Valley Housing Market Update: September 2026 Prices, Trends & City-by-City Data The median...
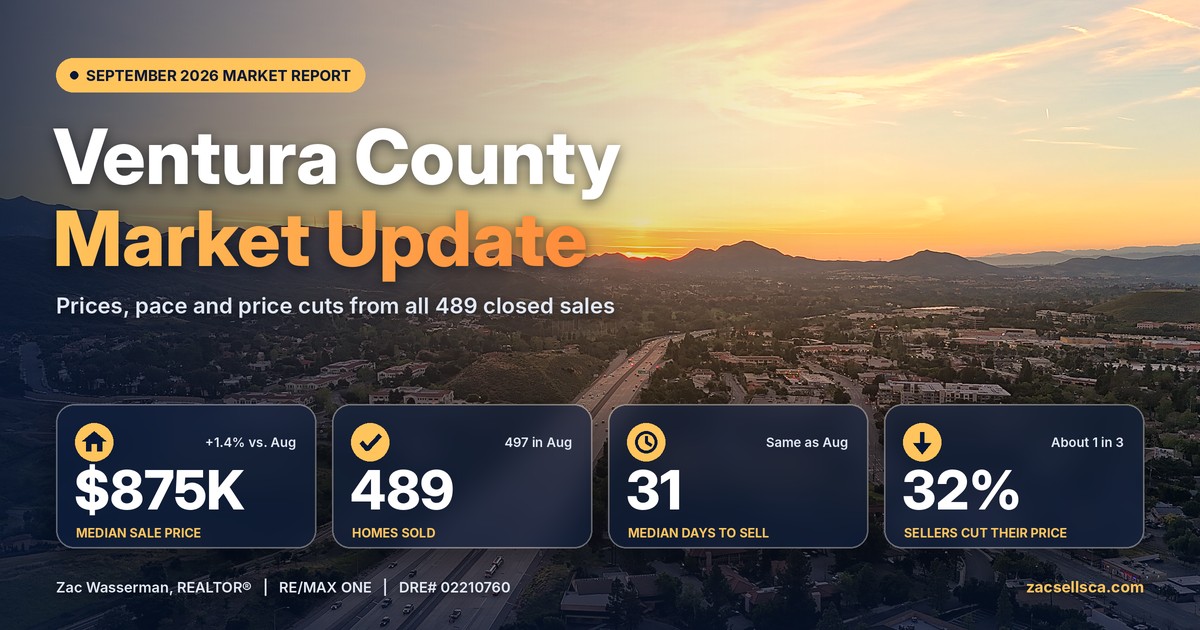
Ventura County’s September 2026 housing market: $875K median price, 489 closed sales, 31 days on market, and city-by-city data for...
State Farm filed to start writing new California home policies again, but only for homes with an IBHS Wildfire Prepared...
Encino real estate in 2026: see median home and condo prices, 494 closed sales, 91436 vs. 91316 trends, neighborhood insights,...