
Ventura County Mortgage Rates: September 2026 Update
Rates have climbed to a one-year high. Here is where mortgage rates stand, why they moved higher, what the upcoming Fed meeting could mean, and how today's rates translate into a real Ventura County home payment.
If you have been keeping an eye on Ventura County mortgage rates this month, here is the honest headline: rates just climbed to a one-year high, and the relief so many buyers have been waiting for has not arrived. As of mid-September 2026, the average 30-year fixed sits near 6.81%, the 15-year fixed is around 6.13%, and a 5/1 adjustable-rate mortgage is running close to 6.56% APR. Therefore, if you were counting on a friendly rate environment this fall, it is time to plan around the market we actually have rather than the one we keep hoping for. As a local REALTOR® with RE/MAX ONE, I would rather give you the real picture than a comfortable one.
Below, I break down exactly where Ventura County mortgage rates stand, why they moved higher, what the September 16 Fed meeting could do, and — most importantly — what all of this means for a real monthly payment on a home here.
Ventura County Mortgage Rates Today: September 2026 Snapshot
Here is where the numbers land as of mid-September 2026:
| Mortgage Type | Mid-September 2026 Rate |
|---|---|
| 30-year fixed | ~6.81% |
| 15-year fixed | ~6.13% |
| 5/1 adjustable-rate mortgage (ARM) | ~6.56% APR |
For context, that 30-year figure is a fresh one-year high. Additionally, the 10-year Treasury yield — the benchmark that mortgage rates track most closely — pushed up near 4.95% this week, which is the real engine behind the move. Keep in mind that Ventura County mortgage rates are national rates applied locally; your quoted rate still depends on your credit score, down payment, loan size, and property type. However, the direction of travel is the same for everyone: up, not down.
Important: These are average, well-qualified rates. Consequently, the number on your loan estimate could come in higher or lower, which is exactly why shopping multiple lenders matters so much right now.
Why Ventura County Mortgage Rates Just Hit a One-Year High
Rates did not climb by accident. Instead, two forces pushed them up together. First, the August jobs report came in hot — roughly 162,000 new jobs against much softer expectations, with unemployment holding at about 4.1%. A strong labor market signals a strong economy, and a strong economy tends to keep inflation sticky. As a result, bond investors demanded higher yields, and mortgage rates followed.
Second, inflation has stayed stubbornly above the Federal Reserve's 2% target. Because of that, the market has largely given up on the idea of near-term rate cuts. In other words, the "rates will fall soon" narrative that dominated late 2025 has quietly reversed. Therefore, Ventura County mortgage rates are not sitting at a one-year high because of anything local — they are elevated because the national inflation-and-jobs story turned hawkish.
The September 16 Fed Meeting: Hike, Hold & What It Means Locally
All eyes are on the Federal Open Market Committee, which announces its next decision on September 16 at 2:00 p.m. Eastern. This meeting is unusual because it is a genuine coin flip. The Fed has held its benchmark rate at 3.50%–3.75% at every meeting this year, and now, for the first time in a while, a rate hike is on the table rather than a cut.
To be clear about the odds: prediction markets currently lean toward a 25-basis-point hike, with the remaining probability on no change, and essentially no one is pricing in a cut. Meanwhile, major forecasters are split — some expect a hike, while others expect the Fed to hold steady through the rest of 2026. Since the committee will also release an updated set of economic projections, the "dot plot" that accompanies this decision could move markets as much as the rate call itself.
Although a hike would confirm a hawkish stance and could nudge rates higher, mortgage pricing has already moved in anticipation. Consequently, if the Fed hikes as expected, much of that is baked in; however, if the Fed surprises with a hold and a dovish tone, we could actually see a small pullback in rates. Either way, do not expect a dramatic drop this month.
What Today's Rates Mean for a Ventura County Home Payment
This is where national headlines stop being useful and local math takes over. The median home price in Ventura County was about $862,500 as of August 2026, so let me show you what current Ventura County mortgage rates do to a real payment at that price point.
With 20% down ($172,500), you are financing $690,000.
| Loan | Rate | Principal & Interest |
|---|---|---|
| 30-year fixed | 6.81% | about $4,503/month |
| 15-year fixed | 6.13% | about $5,871/month |
With 10% down ($86,250), you are financing $776,250.
| Loan | Rate | Principal & Interest |
|---|---|---|
| 30-year fixed | 6.81% | about $5,066/month |
Remember, those figures cover principal and interest only. In addition, you will layer on property taxes, homeowners insurance, and — with less than 20% down — mortgage insurance. Because insurance costs have risen sharply across our county, that "everything else" line matters more here than it did a few years ago. If you want to pressure-test your own price point, how much house can I afford in Ventura County walks through the full budget, and you can also run your own numbers on our mortgage calculator.
One more local wrinkle: because the county median sits close to the conforming loan ceiling, many Ventura County buyers land in jumbo-loan territory, which can carry different pricing. For that reason, it is worth reviewing the 2026 conforming and jumbo loan limits before you assume which bucket you are in.
30-Year vs. 15-Year vs. ARM in a High-Rate Market
When Ventura County mortgage rates are elevated, loan structure becomes a real lever. Here is how I frame it for clients.
The 30-year fixed remains the default for a reason: it keeps your monthly payment as low as a fixed loan allows, which protects cash flow in an expensive market. However, you pay far more interest over time.
The 15-year fixed comes with a lower rate and builds equity aggressively, yet the monthly payment jumps significantly — in our example, nearly $1,400 more per month. Therefore, it fits buyers with strong income and lower other obligations.
An ARM offers a lower starting rate, which can help you qualify or reduce early payments. On the other hand, the rate can adjust later, so an ARM makes the most sense if you realistically expect to sell or refinance within the fixed period. Since nobody can promise where rates go next, I always walk clients through the reset math before they choose this path.
The Real Cost of Waiting for Lower Ventura County Mortgage Rates
Many buyers tell me they will simply wait for rates to fall.
That instinct makes sense, and it might work out. Still, waiting is a tradeoff rather than a clear win, so it helps to look at both sides honestly.
Here is the part that often gets overlooked: mortgage rates and buyer competition tend to move together. If Ventura County mortgage rates do come down, borrowing gets cheaper for everyone at once, not just for you. Lower rates typically pull more buyers off the sidelines, and more buyers competing for the same homes can push offers higher and shrink your negotiating room. In other words, a lower rate can arrive alongside a more competitive market, and the two can partly cancel each other out.
Now consider the flip side, because it is just as real. If rates fall and prices hold steady, waiting could genuinely improve your affordability and lower your monthly payment. That outcome is possible. It is simply not guaranteed, and neither the direction of rates nor the direction of prices is something I can promise you.
A quick illustration helps, using the same $690,000 loan from earlier. At 6.81%, that payment runs about $4,503 a month, and a quarter-point move in either direction shifts it by roughly a hundred dollars a month. That works in your favor if rates drop and against you if they rise, which is exactly why timing the market perfectly is so difficult.
So how do I frame it for clients? Rather than waiting for a specific number, I look at whether the home and the payment work for your situation today. If they do, buying now and keeping an eye on refinancing later is often reasonable. If the payment feels like a stretch, waiting or adjusting your price range may be the smarter call. There is no universally right answer here — only the one that fits your budget, your timeline, and the home in front of you.
How to Lock a Lower Rate Right Now (Buydowns, Credit, Shopping)
You are not powerless against high Ventura County mortgage rates. On the contrary, several levers can meaningfully lower your rate or payment today.
- Shop three to five lenders on the same day. Rates and fees vary more than most buyers expect, and a single day keeps the comparison apples-to-apples. This alone can save thousands.
- Ask about a temporary or permanent buydown. In today's market, sellers are increasingly willing to fund a 2-1 buydown as a concession, which lowers your rate in the early years.
- Strengthen your credit before you apply. Even a modest score bump can move your rate, so pay down balances and avoid new debt in the months beforehand.
- Increase your down payment where possible. More equity can improve pricing and, at 20%, eliminates mortgage insurance entirely.
- Consider points. If you plan to stay put for many years, paying to buy the rate down can pay off over time.
Additionally, get fully underwritten — not just pre-qualified — before you shop. In a market moving this fast, a strong pre-approval is negotiating power.
What Higher Ventura County Mortgage Rates Mean for Sellers
If you are selling, higher Ventura County mortgage rates change your buyer pool, but they do not spell trouble. Because rates squeeze affordability, buyers are more payment-sensitive and more likely to negotiate on price or ask for a rate buydown. Therefore, sharp pricing and a willingness to offer a concession — rather than a blanket price cut — often net you more.
The good news is that our market remains fundamentally healthy. With roughly 3.2 months of supply, Ventura County still leans toward sellers, and well-prepared homes are moving in about a month at nearly full asking price. Consequently, the strategy is not to panic but to prepare: price to the current payment reality, present the home flawlessly, and be ready to negotiate creatively. If you are curious where your home stands today, you can start with a free home valuation.
For the underlying rate data referenced throughout this update, the Freddie Mac Primary Mortgage Market Survey is the weekly benchmark I trust most.
What to Do About Ventura County Mortgage Rates Right Now
With Ventura County mortgage rates near current levels, the most useful move is to shift your focus from the headline rate to your actual numbers. Rates will do what they do, and no one — myself included — can time them perfectly. What you can control is whether the home and the monthly payment make sense for your life today.
Start there. Get clear on the payment you are comfortable with, then work backward to a price range and a loan structure that fits. Compare at least a few lenders on the same day, since rate and fee quotes vary more than most buyers expect, and make sure you understand the full monthly cost — principal, interest, taxes, and insurance — not just the rate on the sheet.
If rates improve down the road, refinancing may give you a chance to lower that payment later. Keep in mind, though, that refinancing is never guaranteed; it depends on where rates go, your equity, and your qualifications at that time. So treat a future refinance as a possible bonus, not part of today's plan.
The buyers who tend to do well in a market like this are not the ones who guess the bottom in interest rates. They are the ones who buy a home they can comfortably afford, at a payment that works, and stay flexible about the rest.
Frequently Asked Questions About Ventura County Mortgage Rates
What are current Ventura County mortgage rates in September 2026?
As of mid-September 2026, Ventura County mortgage rates average about 6.81% for a 30-year fixed, 6.13% for a 15-year fixed, and 6.56% APR for a 5/1 ARM. These are national averages applied locally, so your actual rate depends on your credit, down payment, and loan size. That 30-year figure is currently a one-year high.
Does the Federal Reserve directly control mortgage rates?
Not directly. The Fed sets its benchmark rate, currently 3.50%–3.75%, which influences short-term borrowing. Mortgage rates instead track the 10-year Treasury yield, near 4.95% this week. Because the market anticipates the Fed's moves, mortgage pricing often shifts before a decision, and a Fed change does not translate one-for-one into your mortgage rate.
Should I wait for lower Ventura County mortgage rates before buying?
There is no guaranteed answer. If rates fall and prices hold, waiting could improve your affordability. However, lower rates often draw more buyers into the market, which can increase competition. Rather than timing rates perfectly, focus on whether the home and monthly payment work for you today, since refinancing may be possible later but is never guaranteed.
Should I choose a 30-year, 15-year, or ARM in Ventura County?
It depends on your goals. A 30-year fixed keeps payments lowest and protects cash flow. A 15-year fixed carries a lower rate and builds equity faster, but the payment is significantly higher. An ARM offers a lower starting rate that can adjust later, so it fits buyers who expect to sell or refinance within the fixed period.
What is the monthly payment on a median-priced Ventura County home right now?
On the roughly $862,500 August 2026 median with 20% down, a 30-year fixed at 6.81% runs about $4,503 per month in principal and interest, while a 15-year fixed at 6.13% runs about $5,871. With 10% down, the 30-year payment is about $5,066. Taxes, insurance, and any mortgage insurance are additional.
Mortgage rates are only one part of the equation. I can help you look at price, financing structure, location, monthly payment, and the actual homes available so you can make a decision based on the full picture.
Talk Through Your Options
|
About Zac Wasserman
REALTOR® · RE/MAX ONE · CA DRE# 02210760
Zac Wasserman is a licensed REALTOR® with RE/MAX ONE serving Ventura County and surrounding Southern California communities. He helps buyers and sellers understand local pricing, financing, market conditions, and the practical numbers behind a real estate decision. Phone: 805.212.9147 · Email: ZacSellsCA@gmail.com · Website: zacsellsca.com |
- All Posts
- Buyer Guides
- California Home Insurance & Wildfire Risk
- Home Financing (Mortgage & Loan Guides)
- Market Updates & Forecasts
- Seller Guides
- Back
- Ventura County Real Estate Market Updates
- San Fernando Valley Real Estate Market Updates (Monthly): Prices, Inventory & Trends
MLS closed residential sales • October 1, 2025–October 16, 2026 Median Home Price Woodland Hills CA (2026) Woodland Hills ...
New California real estate laws 2027 change what you can build, what your HOA can block, and how much notice...
Ventura County Mortgage Rates October 2026 October 2026 Mortgage Market Update Ventura County Mortgage Rates October 2026: 7.4% and What...
Ventura County Home Seller Guide | Fall / Winter 2026 Should You Sell Now or Wait Until Spring? Ventura County...
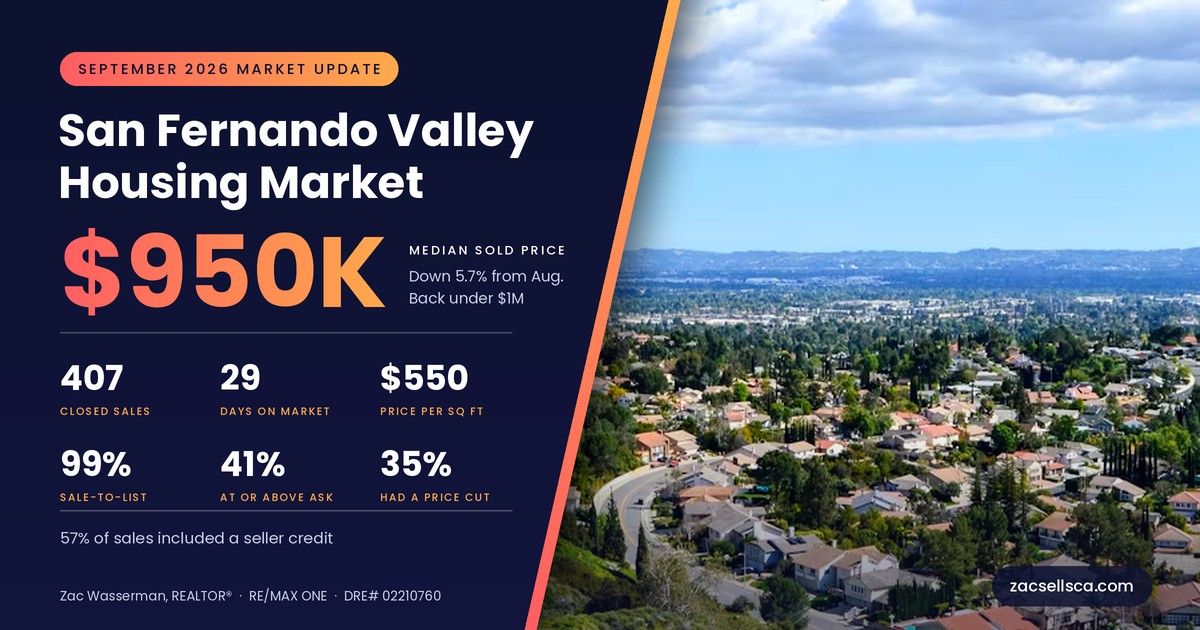
SEPTEMBER 2026 · MARKET UPDATE San Fernando Valley Housing Market Update: September 2026 Prices, Trends & City-by-City Data The median...
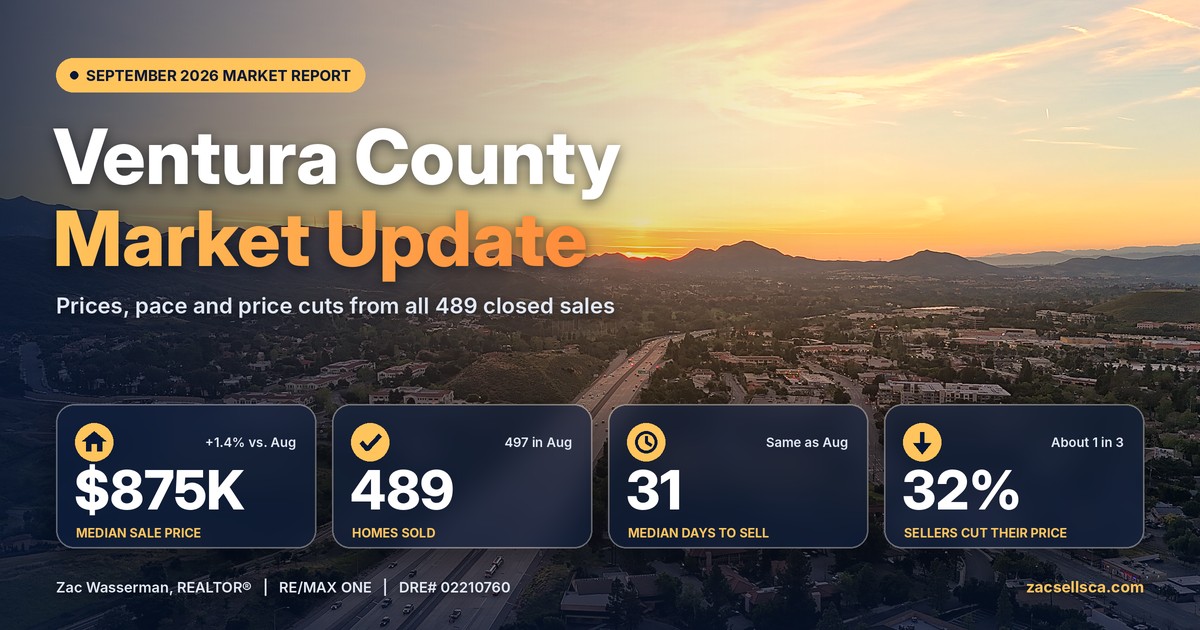
Ventura County’s September 2026 housing market: $875K median price, 489 closed sales, 31 days on market, and city-by-city data for...