
Can You Sell an ADU Separately in California? Your 2026 AB 1033
Can You Sell an ADU Separately in California? Your 2026 AB 1033 Guide for LA & Ventura County Sell an ADU Separately in California (AB 1033) If you built a backyard unit to add income or house family, you have probably wondered whether you can sell an ADU separately from your main home and cash in on that equity. It is one of the most common questions I hear from homeowners across Ventura County and the San Fernando Valley, and the honest 2026 answer has real nuance. A California law called AB 1033 made separate sales possible in theory. However, whether it applies to your property depends entirely on where you live. In this guide, I will walk you through exactly what AB 1033 does, where it stands locally right now, and how to position yourself if your city eventually opts in. I am Zac Wasserman, a licensed REALTOR with RE/MAX ONE, and I help buyers and sellers navigate exactly these kinds of gray areas every week. Let’s clear up the confusion. What AB 1033 Actually Does (and What It Doesn’t) Assembly Bill 1033 was signed into law in October 2023 and took effect on January 1, 2024. In plain terms, it added a new section to California’s planning code that gives cities and counties the authority to let homeowners sell an accessory dwelling unit as its own condominium, separate from the primary house on the same lot. Before this law, an ADU was legally tied to the main home and could not be sold on its own. Here is the catch that trips up most homeowners, though. AB 1033 is permissive, not mandatory. In other words, the state did not automatically unlock separate ADU sales everywhere. Instead, each individual city or county must affirmatively pass its own local ordinance before any homeowner in that jurisdiction can take advantage of the law. As a result, the map of where this actually works is patchy, and it is changing slowly. Additionally, it helps to understand what the law does not do. AB 1033 does not create new types of ADUs, loosen construction rules, or override your local zoning. Furthermore, it does not turn your existing rental unit into an instant sellable asset. It simply changes what can legally happen to a permitted ADU after it is built, and only in places that have opted in. The key distinction California allows local governments to create an AB 1033 program. The law does not automatically give every California homeowner the right to sell an ADU separately. Can You Sell an ADU Separately in California Right Now? For most of the state, the short answer is still no. As of 2026, only a small number of California jurisdictions have adopted the local ordinance required for a separate ADU sale. San Jose led the way and completed the state’s first separate ADU sale in 2025. Santa Monica followed with its own ordinance, and unincorporated San Diego County adopted a program that took effect in April 2026. A few other cities are studying or drafting ordinances, but the list of places where this is fully operational remains short. Consequently, whether this option is even available to you comes down to one question: has your specific city or county opted in? If the answer is no, then under default state law your ADU still cannot be sold apart from the main house, no matter how nice or independent the unit is. This is why I always tell homeowners to confirm their local status before making any decision based on AB 1033. AB 1033 Status in Los Angeles and Ventura County (2026) Now for the part that matters most to my clients. As of 2026, neither Los Angeles nor Ventura County allows the separate sale of an ADU. Let’s break it down by area. Ventura County In Ventura County, the county updated its ADU ordinance in 2024 to align with state law, and it applies to all unincorporated areas through the Resource Management Agency. However, that ordinance does not implement an AB 1033 separate-sale program. Moreover, none of the county’s ten incorporated cities, including Thousand Oaks, Camarillo, Simi Valley, Oxnard, and Ventura, has adopted its own AB 1033 ordinance yet. Therefore, if you own an ADU anywhere in Ventura County today, you cannot sell it separately from your primary residence. Los Angeles The picture is similar in Los Angeles. The City of Los Angeles introduced a council motion back in 2025 to explore AB 1033, but that motion has not advanced into an adopted ordinance. Likewise, unincorporated Los Angeles County has not adopted a separate-sale program, and neighboring cities such as Pasadena, Glendale, and Alhambra remain on the sidelines as well. In short, the entire LA-to-Ventura corridor that I serve is currently a “not yet” zone. That said, local policy can shift quickly, and housing pressure keeps AB 1033 on the agenda. For that reason, it is worth understanding how the process would work so you are ready to move the moment your city acts. Your ADU may not be separately sellable yet — but it can still affect what your property is worth today. If you own a home with an ADU in Ventura County or the San Fernando Valley, I can help you look at the property as a whole and understand how buyers may value the additional living space and income potential. Get a Free Home Valuation Call or Text 805.212.9147 How the ADU Condo Conversion Process Works Selling an ADU separately is not as simple as listing it and finding a buyer. Because the law treats the ADU as a condominium, you essentially convert your single lot into a two-unit condo project. Here is the general path in jurisdictions that allow it. 1 The ADU must be fully permitted and have received its certificate of occupancy. 2 A surveyor and civil engineer prepare the required condominium mapping. 3 A condominium plan is recorded and separate ownership interests are created. 4 CC&Rs are recorded
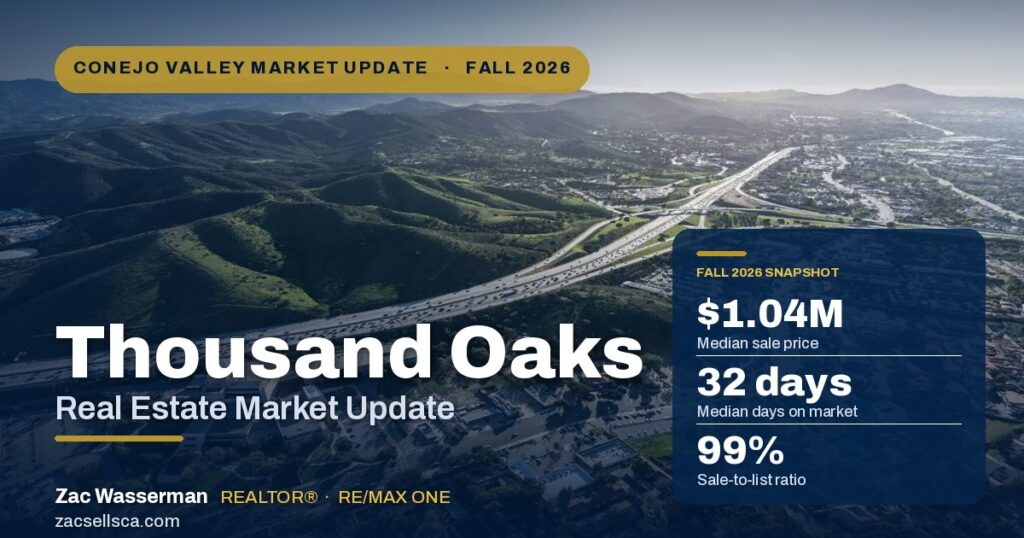
Thousand Oaks Real Estate Market Update: Fall 2026
Can you sell an ADU separately in California under AB 1033? See the 2026 status for Ventura County and Los Angeles, plus costs, financing, and how homeowners can prepare.
San Fernando Valley Housing Market Update: August 2026 Prices, Trends & City-by-City Data
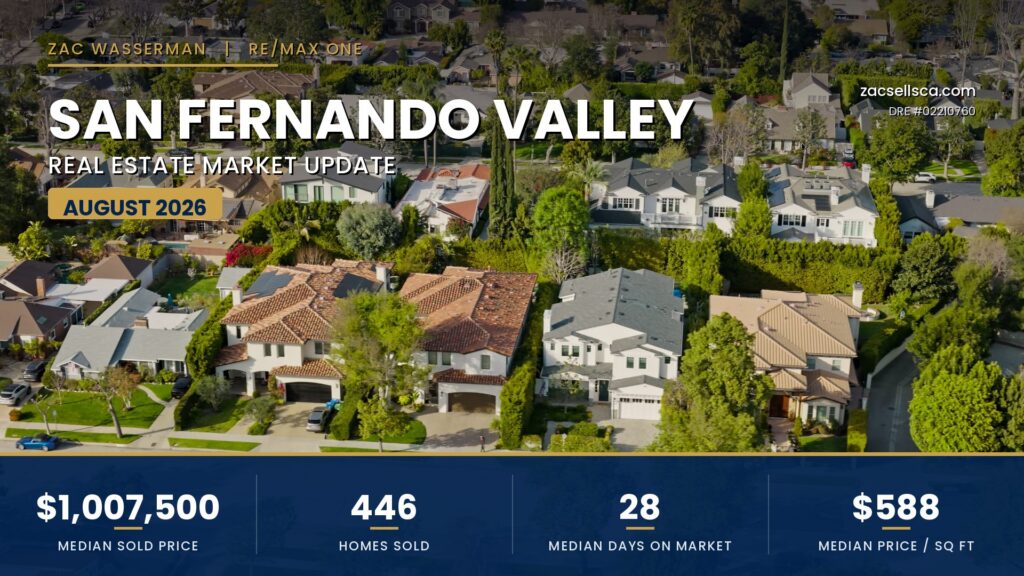
August 2026 • Local Market Report San Fernando Valley Housing Market Update: August 2026 Prices, Trends & City-by-City Data By Zac Wasserman, REALTOR®RE/MAX ONE • CA DRE# 02210760 Get My Free Home Valuation Plan My Next Move If you have been watching the San Fernando Valley housing market this summer, August delivered a clear message: prices are holding firm, well-priced homes are still moving quickly, and buyers finally have a touch more room to negotiate. As a licensed REALTOR® with RE/MAX ONE who works these neighborhoods every week, I pulled the closed-sale data for every San Fernando Valley community and broke it down so you can see exactly where the market stands heading into fall. Across the Valley, 446 homes closed escrow in August 2026. The numbers tell a story of a market that has settled into a steadier, more balanced rhythm than the frenzy of a few years ago — yet remains firmly a seller’s market in most price ranges. Let’s dig into what actually happened, city by city, and what it means whether you plan to buy, sell, or simply keep an eye on your home’s value. The San Fernando Valley Housing Market at a Glance: August 2026 Here is the high-level snapshot for all closed residential sales across the Valley last month: Median sold price (all homes): $1,007,500 Median price per square foot: $588 Median days on market: 28 Median sale-to-list ratio: roughly 99% Homes sold at or above asking: about 44% Total closed sales: 446 Therefore, the headline number is that the typical San Fernando Valley home is still closing right around the seven-figure mark. However, the more interesting signal sits just beneath it. Homes are selling at about 99% of their final list price, and only around 44% closed at or above asking — a meaningful shift from the days when nearly everything sold over list with multiple offers. Additionally, sellers gave up a little ground from their original asking price, with the typical home closing near 98% of where it first launched. As a result, pricing precision matters more now than it has in years. Meanwhile, mortgage rates stayed in the mid-6% range through August. According to Freddie Mac’s Primary Mortgage Market Survey, the 30-year fixed averaged 6.71% in early September — modestly higher than a year ago, but stable enough that buyers have adjusted their expectations rather than stepping away entirely. San Fernando Valley Median Home Prices in August 2026 The median home price is simply the midpoint — half of all homes sold for more, and half for less — which makes it a far more reliable gauge of the local market than the average, because a handful of multimillion-dollar estates can drag an average sky-high. In August, that Valley-wide median landed at $1,007,500. However, “the Valley” is really a patchwork of very different markets. Consequently, breaking the data down by property type reveals how wide the range truly is: Single-family homes: median $1,182,500 (median $609/sq ft, 27 days on market) Condominiums: median $495,000 (median $446/sq ft, 32 days on market) Townhomes: median $610,000 (median $367/sq ft, 31 days on market) In other words, a detached house in the Valley now runs nearly $1.2 million at the midpoint, while a condo remains one of the region’s most attainable footholds at under half a million. For buyers priced out of a single-family home, that spread is exactly why condos and townhomes keep drawing first-time and move-down buyers. Furthermore, for anyone weighing whether to stretch for a house, it helps to know precisely how much house can I afford in Los Angeles before touring anything. How Fast Are Homes Selling? Days on Market & Sale-to-List Speed tells you as much about a market as price does. In August, the median San Fernando Valley home went from active to pending in 28 days. Moreover, the pace was even quicker for sharply priced listings: roughly one-third of all homes sold within 14 days, and more than half were in escrow inside a month. That said, the market is no longer indiscriminate. Because buyers are more rate-conscious and more selective, the homes that linger tend to share a common thread — they launched above what the data supported. When a listing is priced correctly from day one, it still commands strong attention and frequently multiple offers. When it is not, it sits, and the eventual sale lands below the original ask. This is the single most important dynamic in today’s San Fernando Valley housing market: precision beats optimism. The sale-to-list ratio reinforces the point. At a median near 99%, sellers are still capturing almost all of their asking price. Nevertheless, the fact that fewer than half of homes closed over asking signals that the bidding-war reflex has cooled. For sellers, that makes an accurate, current valuation essential — and if you are curious what your own home would fetch in this market, you can start with a free home valuation. San Fernando Valley Home Prices by City This is where the Valley’s true character shows up. The following table breaks down median sold prices by city for August 2026, covering every community with a meaningful number of closed sales. As you will see, the Valley’s housing market spans well over a million dollars in range from its most affordable neighborhoods to its priciest enclaves. On smaller screens, scroll horizontally to see every column. August 2026 • Closed Residential Sales by City City Median Sold Price Median $/Sq Ft Median Days on Market Sale-to-List Encino $2,050,000 $699 36 99% Calabasas $1,911,500 $711 49 99% Studio City $1,900,500 $822 41 97% Sherman Oaks $1,427,500 $675 25 98% Tarzana $1,325,000 $604 37 98% Woodland Hills $1,215,500 $590 25 97% Northridge $1,100,000 $643 31 100% West Hills $1,040,000 $408 15 96% Chatsworth $905,000 $533 18 91% North Hollywood $850,000 $588 27 100% Winnetka $805,000 $484 24 100% Van Nuys $780,000 $485 36 100% Reseda $763,000 $410 28 100% Panorama City $717,500 $511 22 103% Canoga Park $560,000 $575 25 100%
Ventura County Real Estate Market Update: August 2026
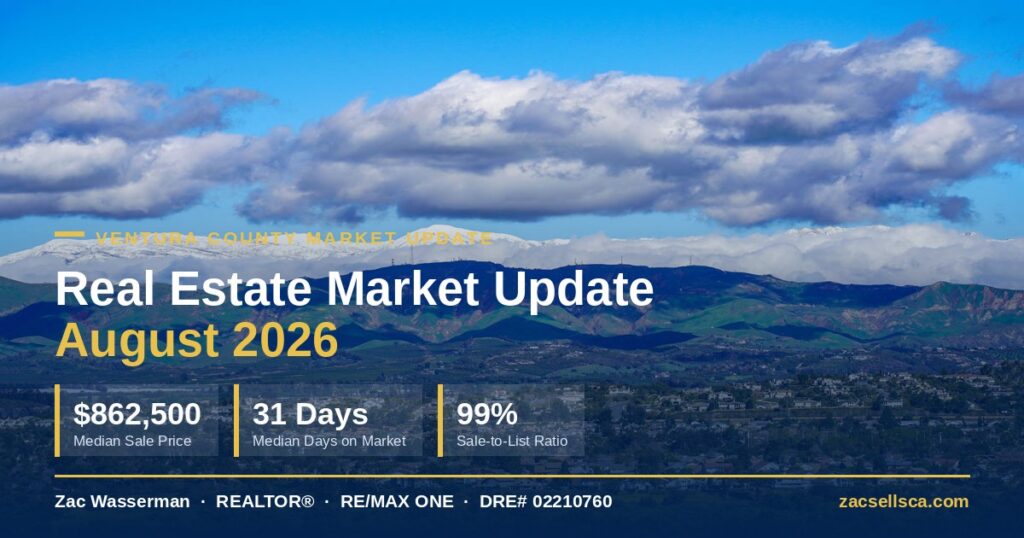
Ventura County Real Estate Market Update: August 2026 Ventura County Market Update — August 2026 Ventura County Real Estate Market Update: August 2026 If you have been watching home prices in our area and wondering where things actually stand, this Ventura County real estate market update for August 2026 gives you the real numbers. I pulled every closed sale across the county for the month—497 in total—and broke them down by price, days on market, and city. As a licensed REALTOR® with RE/MAX ONE, my goal here is simple: give you an honest, data-first read so you can make a confident decision, whether you are buying, selling, or simply keeping an eye on your equity. The short version? Ventura County remains a firm, well-balanced market. Prices are holding, well-priced homes are still moving quickly, and sellers are collecting very close to their asking price. However, the pace varies a lot depending on your city and price point, and that nuance is exactly where opportunity lives. Throughout this report, I will translate the raw data into what it practically means for your next move. Get My Free Home Valuation Call Zac: 805-212-9147 Ventura County Real Estate Market Update at a Glance (August 2026) Let’s start with the headline figures. Across all 497 closed sales in August, the median sale price landed at $862,500. The average sale price was noticeably higher at roughly $1.1 million, but that gap tells a story: a handful of luxury closings—including a $6.67 million Somis estate and a $6.24 million Thousand Oaks property—pull the average upward. As a result, the median is the more reliable number for most buyers and sellers, because it reflects the typical home rather than the outliers. Here are the county-wide vitals for the month: Median Sale Price $862,500 All property types Single-Family Median $959,500 Detached homes Median Days on Market 31 Days Countywide Sale-to-List Ratio 99% Typical sale Price Per Sq. Ft. $511 Countywide median At / Above Asking 43% Of August sales Cash Purchases ~10% Roughly 1 in 10 sales Additionally, single-family homes made up the bulk of activity, with 374 of the 497 closings. Condominiums accounted for 71 sales and townhomes another 46, so buyers seeking lower price points still had meaningful attached-home inventory to choose from. In short, this was a broad, active month rather than a market propped up by one narrow segment. For Ventura County Homeowners What do these August numbers mean for your home? Countywide statistics are useful, but your neighborhood, condition, lot, upgrades, and exact price range determine what buyers are likely to pay. Get a local value range based on today’s market. Request a Free Home Valuation Median Home Prices Across Ventura County At a $862,500 countywide median, Ventura County continues to sit in a healthy, move-up-friendly range. Furthermore, the spread of sales shows a market with real depth at every level. In August, 31 homes closed under $500,000, while 121 sold between $500,000 and $750,000. The largest slice—164 sales—fell in the $750,000 to $1 million band, followed by 112 sales between $1 million and $1.5 million. Finally, 69 homes traded above $1.5 million, including 39 above the $2 million mark. August Sales by Price Range 31 Under $500K 121 $500K–$750K 164 $750K–$1M 112 $1M–$1.5M 69 Above $1.5M Because inventory is spread so evenly across price tiers, this is not a market that only serves one type of buyer. First-time buyers, move-up families, and luxury purchasers all found homes that closed in August. The countywide median of $511 per square foot is another useful anchor, though it varies widely by city—from the mid-$300s in Santa Paula to roughly $675 in Westlake Village. If you are trying to gauge your own buying power against these prices, my guide on how much house can I afford in Ventura County walks through the math step by step. How Fast Are Homes Selling? Days on Market in August 2026 31 Median days on market 29% Closed in 2 weeks or less Speed is one of the clearest signals of market health, and here the data is encouraging for sellers. The median home spent just 31 days on market before going under contract. Even better, 29% of all August sales closed in two weeks or less, which tells you that sharply priced, well-presented homes are still commanding urgency. However, the average days on market—about 46—ran higher than the median. Consequently, this reveals a two-speed market: turnkey, correctly priced homes fly, while overpriced or dated listings sit and eventually negotiate. In other words, presentation and pricing strategy matter more than ever. Therefore, if you are preparing to list, the pre-market prep work is where deals are won or lost. A home that launches clean, staged, and priced to the comparables can still generate the kind of early urgency that leads to a strong offer. Are Homes Selling Over Asking? Sale-to-List Trends The county’s median sale-to-list ratio held at a strong 99% in August, meaning the typical seller collected 99 cents on every dollar of their asking price. Moreover, 43% of homes closed at or above their list price, and 17% sold for more than asking outright. That is a clear sign that competitive, in-demand properties are still drawing multiple offers. 99% Median sale-to-list ratio 43% Closed at or above asking 17% Sold above asking On the other hand, 43% of sales closed below asking, which underscores the same lesson from the days-on-market data. When a home is priced ahead of the market, buyers push back. Since roughly one in ten buyers paid cash, sellers who prepare well and price to the comps are the ones capturing top dollar. This balance—firm but not frenzied—is what makes the current market feel so stable compared to the extremes of recent years. Ventura County Real Estate Market Update by City County averages are useful, but real estate is hyper-local, so here is how each major city performed in August. The list below covers every city with at least eight closed sales for the
Ventura County Foreclosures in 2026: How to Buy Smart or Sell Fast
Ventura County Real Estate Guide • 2026 Ventura County Foreclosures in 2026: How to Buy Smart or Sell Fast A practical local guide for foreclosure buyers and Ventura County homeowners who may need to sell before a trustee sale. If you have been watching Ventura County foreclosures in 2026, you are not alone. Search interest has climbed as higher ownership costs put pressure on some homeowners, and buyers hunting for a deal want to know where the opportunities are. As a licensed REALTOR® with RE/MAX ONE, I get calls from both sides of this conversation every week: buyers asking how to find a bank-owned bargain, and homeowners quietly asking how to get out from under a mortgage before the bank forecloses. This guide covers both, because Ventura County foreclosures are really two markets wearing one label. First, let me set expectations honestly. Foreclosures are not the flood of cheap inventory some people imagine. However, they are a real and growing slice of the market, and understanding how the process works locally gives you a genuine edge, whether you are buying or selling. Buying or selling under pressure? The right strategy depends on whether you are pursuing a distressed property or trying to protect your equity before foreclosure. The sections below break down both paths. Get a Free Home Valuation Ventura County Foreclosures in 2026: Where the Market Stands Nationally, foreclosure activity has been climbing steadily. According to ATTOM’s mid-year 2026 report, roughly 227,548 U.S. properties received a foreclosure filing in the first half of the year, up about 21% from the same period in 2025. California ranked among the top states, with more than 16,000 foreclosure starts in that six-month window. Therefore, the trend is clearly upward. That said, context matters. Even with the annual increase, foreclosure volume remains low by historical standards, nowhere near the 2008 to 2011 era. Additionally, foreclosure timelines have been shrinking; homes completing the process in Q2 2026 averaged about 563 days, the shortest stretch since 2013. As a result, distressed properties are moving through the pipeline faster than they did a few years ago. For Ventura County specifically, the takeaway is simple. Foreclosure inventory exists, it is growing modestly, and it competes inside a market that is otherwise still tight on supply. If you want the broader picture on prices and inventory, my breakdown of the Ventura County housing market 2026 pairs well with this guide. How Foreclosure Works in California (Non-Judicial Process) Before you chase Ventura County foreclosures, you need to understand the California timeline, because it determines when and how a property becomes available. California is primarily a non-judicial foreclosure state. In plain terms, that means the lender does not have to sue the homeowner in court; instead, the process runs through the deed of trust and a trustee. Consequently, foreclosures here move faster than in judicial states like New York or Florida. First, the homeowner falls behind. After about 90 days of missed payments, the lender records a Notice of Default (NOD). This is the official start, and it becomes public record. Next comes a 90-day reinstatement window. During this time, the homeowner can catch up on back payments and stop the process. Many do, which is exactly why a Notice of Default does not guarantee a sale. Then, if the default is not cured, the lender records a Notice of Trustee Sale (NTS). The auction must be scheduled at least 21 days after this notice is recorded. Finally, the property goes to a public trustee sale, usually on the courthouse steps or online. If nobody buys the home at auction, it reverts to the lender and becomes an REO, or “real estate owned,” property. At that point, it typically gets listed on the open market like any other home. It is also worth knowing that California’s Homeowner Bill of Rights adds protections for owners in default, including restrictions on “dual tracking” (foreclosing while a loan modification is under review) and a requirement that servicers provide a single point of contact. These rules matter for distressed sellers, and I will come back to them below. Where to Find Foreclosure Homes for Sale in Ventura County Once you understand the stages, finding foreclosure homes for sale in Ventura County becomes much more logical, because each stage has its own place to look. Pre-foreclosures and Notices of Default are recorded at the Ventura County Recorder’s office and aggregated by subscription data services. However, these are not “for sale” yet; the owner still controls the property. Trustee sale listings appear through the trustee companies handling each auction, along with third-party auction platforms. Additionally, the Notice of Trustee Sale itself is public. REO and bank-owned homes are the easiest to access, because they show up right on the MLS, often flagged as “bank owned,” “REO,” or “corporate owned.” In other words, most everyday buyers will interact with foreclosures at the REO stage, through a normal agent-assisted purchase. Because so much foreclosure data lives behind paywalls or in public records that are tedious to search, working with a local agent who monitors these channels saves enormous time. That is a core part of what I do for buyer clients. Buying a Ventura County Foreclosure: Three Ways In There are three distinct entry points, and they carry very different risk levels. Let me walk through each. Option 1: Pre-Foreclosure or Short Sale Here, you approach a homeowner who is behind but has not yet lost the property, or you negotiate with the lender to accept less than the balance owed. This route can produce real discounts. However, short sales are slow and require lender approval, so patience is essential. Option 2: Trustee Sale Auction This is the highest-risk, highest-reward path. You often must pay all cash, close almost immediately, and buy the property sight-unseen and as-is, sometimes with existing liens or occupants still inside. For that reason, auctions are best left to experienced investors, not first-time buyers. Option 3: REO or Bank-Owned Purchase This is the
California FAIR Plan Rate Increase 2026: What It Means for Ventura County Homeowners
California FAIR Plan Rate Increase 2026: What It Means California FAIR Plan Rate Increase 2026: What It Means for Ventura County Homeowners Ventura County Homeowner Update California FAIR Plan Rate Increase 2026: What It Means for Ventura County Homeowners The 29.1% increase begins October 15, 2026. Here is what homeowners, buyers, and sellers need to know—and how to plan with confidence. Talk With Zac About Your Next Move The California FAIR Plan rate increase 2026 is now official, and it lands on October 15, 2026. If you own a home in a wildfire-exposed part of Ventura County or the San Fernando Valley, this change matters — and if you are buying or selling this fall, it matters even more. As a licensed REALTOR® with RE/MAX ONE, I watch insurance shifts closely, because insurability increasingly decides whether a deal closes at all. Below, I break down exactly what the 29.1% increase does, why it is happening, and what it means for your home value and your next move. The short version Insurance is now part of the price, financing, and marketability of a home. Quote early, document mitigation work, and build the real premium into every decision. What the California FAIR Plan Rate Increase Means for 2026 First, the headline. The California Department of Insurance approved a statewide average increase of 29.1% for the FAIR Plan, the state’s insurer of last resort. Furthermore, the new rates take effect on all new and renewal dwelling policies dated October 15, 2026 or later. The FAIR Plan originally requested a 35.8% hike; however, the Department trimmed it to 29.1%. Even so, this remains the largest single-year increase in the plan’s history. It helps to remember what the FAIR Plan actually is. Essentially, it is a shared pool that provides basic fire coverage to homeowners who cannot find a policy on the standard market. Additionally, it is dwelling-fire coverage only — it covers fire, smoke, lightning, and internal explosion, but not theft, liability, or water damage. As a result, most FAIR Plan policyholders also carry a separate “wrap” or Difference in Conditions (DIC) policy to fill the gaps. For a full breakdown of how those two policies fit together, see my guide to home insurance and the FAIR Plan across Ventura and LA. Why the FAIR Plan Rate Increase Is Happening The reasons behind the California FAIR Plan rate increase 2026 are not complicated, though they are sobering. Over the past several years, major carriers such as State Farm and Allstate pulled back from wildfire-prone areas across California. Consequently, hundreds of thousands of homeowners were pushed onto the FAIR Plan because they had nowhere else to go. The numbers tell the story. As of mid-2026, the FAIR Plan’s total exposure reached roughly $768 billion — an increase of about 250% since 2022. Meanwhile, the plan now covers close to 700,000 policyholders. Then came the January 2025 Los Angeles wildfires, which generated an estimated $4 billion in FAIR Plan losses and forced the plan to assess its member insurers $1 billion just to pay claims. Therefore, the rate increase is essentially the plan catching up to a risk pool that has grown far faster than its reserves. For local context, Ventura County is not a bystander here. In fact, FEMA ranks the county in the 99th percentile nationally for overall natural-disaster risk, with wildfire at the 100th percentile. The 2017 Thomas Fire and the 2018 Woolsey Fire are still fresh memories for many families, and both accelerated the insurer pullback we feel today. To understand the local risk picture in depth, my Ventura County wildfire insurance guide walks through it street by street. How the 29.1% Increase Actually Hits Your Premium Here is the part most headlines skip. The 29.1% figure is a statewide average, not a flat number applied to every policy. Because the increase is concentrated in the wildfire portion of the premium, your actual change depends heavily on where your home sits. Specifically, homeowners with significant wildfire exposure will see far more than the average — in some cases, the wildfire portion of their premium will roughly double. On the other hand, homeowners in lower-risk zones may see a smaller increase, and a few may even see their premium hold steady or dip slightly. In short, a hillside home backing to open space and a valley-floor home a few miles away can land in very different places, even on the same street grid. Simple example $3,500 premium + 29.1% ≈ $1,000 more per year That is roughly $85 more each month. To put rough dollars on it, the FAIR Plan already averaged around $3,000 per year as of late 2025, compared with a statewide private-market average closer to $1,571. Once you add a DIC wrap, the combined cost often runs two to three times a standard homeowners policy. Apply the 29.1% increase on top of an already-elevated base, and the monthly impact becomes real money — money that lenders fold directly into your qualifying payment. Because underwriters count that premium against your debt-to-income ratio, a higher insurance bill can quietly shrink your purchasing power by tens of thousands of dollars. What the FAIR Plan Rate Increase Means for Ventura County Home Values Now for the question I get most from clients: does the California FAIR Plan rate increase 2026 actually move home values? The honest answer is that it moves affordability, and affordability moves values. Here is why. When insurance costs climb, the buyer’s total monthly payment climbs with it. Consequently, buyers either qualify for less or negotiate harder on price to offset the carrying cost. Additionally, insurability has become a financing gate: a lender will not fund a loan without proof of coverage, so a home that can only be insured through the FAIR Plan may draw fewer offers or sit longer on the market. For a broader look at where prices are heading, see my Ventura County housing market 2026 update. Importantly, this is not a countywide discount. Rather, it
Best Neighborhoods in Thousand Oaks, CA (2026 Guide)
Explore the best neighborhoods in Thousand Oaks, CA for 2026 — from North Ranch luxury to family-friendly Dos Vientos. A local REALTOR’s honest guide.
Thousand Oaks vs. Westlake Village: Which Is Right for You in 2026?
Thousand Oaks vs. Westlake Village (2026): Which Is Best? Thousand Oaks vs. Westlake Village 2026 Conejo Valley Buyer’s Guide Thousand Oaks vs. Westlake Village: Which Is Right for You in 2026? Compare home prices, schools, lifestyle, commute, and the county-line detail most buyers miss—then find the community that fits your real life. Compare the Two Cities Get a Free Home Valuation If you’re weighing Thousand Oaks vs. Westlake Village, you’re comparing two of the most sought-after communities in the Conejo Valley — and two markets that feel far more different than their five-mile gap suggests. As a licensed REALTOR® with RE/MAX ONE who lists and sells in both areas every week, I field this exact question constantly, especially from buyers relocating out of Los Angeles. Therefore, I’ve put together an honest, side-by-side breakdown of home prices, schools, lifestyle, commute, and the surprising county-line quirk that confuses almost everyone. By the end, you’ll know which city actually fits your budget and your day-to-day life. Both communities sit at the eastern edge of the Conejo Valley, share the same gorgeous foothill setting, and consistently rank among the safest, most family-friendly places in Southern California. However, they attract very different buyers for very different reasons. So let’s get into it. Thousand Oaks vs. Westlake Village at a Glance (2026) Here’s the quick snapshot before we dig into the details: Factor Thousand Oaks Westlake Village Vibe Large master-planned city Small luxury lakeside enclave Population ~127,000 ~8,000 (incorporated city) Incorporated 1964 1981 County Ventura Los Angeles (incorporated city)* Median home price (2026) ~$1.05M ~$1.5M–$1.8M School district Conejo Valley Unified Las Virgenes / Conejo Valley Unified* Best for Space, value, and selection Prestige, privacy, and the lake *The county and school-district lines are the confusing part — much more on that below. In short, Thousand Oaks gives you scale, selection, and relative value, while Westlake Village gives you exclusivity and a resort-like setting at a premium. Now let’s break down each factor so you can see where you land. Home Prices in Thousand Oaks vs. Westlake Village Price is usually the first place this decision gets real, so let’s start there. As of mid-2026, the median home price in Thousand Oaks sits right around $1.05 million, and it has stayed roughly flat over the past year. Because Thousand Oaks is a large city with everything from condos and townhomes in the $500,000s to custom estates north of $3 million, you get genuine range here. As a result, buyers with a $700,000 to $1.2 million budget find the deepest pool of options anywhere in the county. For a fuller look at the numbers, see my complete breakdown of the median home price in Thousand Oaks. Westlake Village, in contrast, runs meaningfully higher. Depending on which source and metric you use, the typical Westlake Village home value lands somewhere between $1.5 million and $1.8 million in 2026 — roughly 50% above Thousand Oaks. Additionally, because Westlake Village is a small market with relatively few sales each month, its median can swing noticeably from one month to the next. Therefore, I always steer clients toward neighborhood-level pricing rather than a single citywide number. My Westlake Village market update tracks those shifts in more detail. Why the gap? First, Westlake Village skews heavily toward larger, higher-end homes, gated communities, and lakefront or view properties. Second, its scarcity — only a few thousand homes in total — keeps prices elevated. Finally, the prestige factor is real: Westlake Village is routinely described as one of the wealthiest communities in the greater Los Angeles area. Consequently, if your budget tops out near $1 million, Thousand Oaks will simply give you far more house and far more choice. It’s also worth noting the 2026 backdrop. Inventory remains tight across the Conejo Valley, months of supply is low, and well-priced homes still sell quickly in both cities. Statewide, the California Association of REALTORS has tracked this same pattern of limited supply and more cautious buyers throughout 2026. However, buyers today have more negotiating room than they did during the frenzy of a few years ago. As a result, pricing a home correctly from day one matters more than ever — in both markets. Buying or selling in the Conejo Valley? Get a local, address-specific read on value, school boundaries, and current competition before you make your next move. Start with a Free Home Valuation The County-Line Quirk Most Buyers Miss Here’s the part that surprises nearly everyone, and it genuinely affects your search. Most people assume Westlake Village is a Ventura County city. However, the incorporated City of Westlake Village actually sits in Los Angeles County. When the original Westlake master-planned community was developed straddling the county line, California law prevented a single city from spanning two counties. As a result, the Ventura County portion was annexed into Thousand Oaks back in 1968 and 1972, while the remaining Los Angeles County portion incorporated separately as the City of Westlake Village in 1981. What does that mean in practice? Many homes that buyers picture as “Westlake Village” are technically inside Thousand Oaks city limits, in Ventura County. Meanwhile, the official incorporated city — with its own city hall — sits on the LA County side. The county line runs right through Westlake Lake. Because of this split, two nearly identical homes a few blocks apart can fall in different counties, different cities, and different school districts. Therefore, never assume based on the “Westlake Village” label alone — always map the exact address before you write an offer. Schools: How the District Lines Really Work For most families, schools drive this decision as much as price does. Fortunately, both areas are served by highly regarded districts — but which one you get depends entirely on the address. Thousand Oaks, along with the Ventura County side of Westlake Village, falls under Conejo Valley Unified School District (CVUSD). Notably, Westlake High School — located on the Ventura County side and part of CVUSD — is widely considered the
What Is My Home Worth in Oxnard? Your 2026 Home Value Guide
What Is My Home Worth in Oxnard? Your 2026 Home Value Guide Oxnard Home Values • 2026 MLS Data What Is My Home Worth in Oxnard? Your 2026 Home Value Guide Real 2026 Oxnard MLS sale data, ZIP-code pricing, days on market, and the factors that can move your home’s value by six figures. Get My Free Home Valuation What Is My Home Worth in Oxnard? If you own a home along the coast, in RiverPark, or anywhere in between, you have probably typed “what is my home worth in Oxnard” into Google and landed on a Zillow estimate that felt either too high or suspiciously low. As a licensed REALTOR® with RE/MAX ONE serving Ventura County, I hear the same frustration from Oxnard sellers every week. Therefore, instead of guessing, this guide walks you through what real 2026 MLS sale data actually shows, why your ZIP code matters more than you think, and how to get a number you can trust. Let me be clear up front: an automated estimate is a starting point, not an answer. However, the closed sales in your own neighborhood tell the real story, so that is exactly where we will start. 2026 Oxnard Snapshot What Is My Home Worth in Oxnard Right Now? (2026 Snapshot) Over the most recent 90-day period, 210 residential properties closed escrow in Oxnard. Consequently, we have a large, current sample to work from rather than a stale annual average. Here is what those closings show: $802,500 Median Closed Price 20 Days Median Days on Market 100% Median Sale-to-List $517 Median Price / Sq. Ft. Additionally, the picture sharpens when you separate property types. Single-family homes carried a median closed price of $829,750 and sold in a median of just 17 days at $540 per square foot. Condos, by contrast, closed at a median of $642,500, while townhomes landed at $599,000. As a result, the honest answer to what your Oxnard home is worth depends heavily on what kind of home you own before we even discuss location. Furthermore, that 100% sale-to-list ratio is a meaningful signal. Because homes are closing right at asking price and moving in under three weeks, well-priced Oxnard listings still command strong demand in 2026. For a fuller market picture, you can also review my Ventura County market update for the latest county-wide trends. Oxnard Home Values by ZIP Code: Why Location Changes Everything Here is where most online estimates fall apart. Oxnard is not one market — it is at least four, and the price gap between them is enormous. When I pulled the closed sales by ZIP code, the spread was striking: ZIP Code Key Areas Median Closed Price Market Note 93035 Oxnard Shores, Mandalay Bay, the Harbor $1,091,500 Waterfront premium 93036 RiverPark and north Oxnard $770,000 North-Oxnard benchmark 93030 Central and old-town Oxnard $760,000 Central-city benchmark 93033 South and east Oxnard $730,000 11 DOM • 102% of list The ZIP-code gap is more than $360,000. Two similar homes can live in completely different pricing worlds depending on location. In other words, two identical houses can be worth over $360,000 apart depending on which side of the city they sit on. Therefore, any tool that gives you a single “Oxnard” number without accounting for your ZIP code is almost guaranteed to be off. This is also why I always recommend sellers understand the best neighborhoods in Oxnard and where their own street fits in the pricing hierarchy. What Actually Determines Your Oxnard Home’s Worth Beyond ZIP code, several factors move the needle on your home’s value. Since sellers often overweight the wrong ones, let me break down what genuinely matters: Location within the neighborhood Proximity to the beach, water views, and quiet interior streets all carry premiums. Similarly, backing to a busy road or the 101 will pull value down. Condition and updates Because Oxnard’s median home was built around 1980, buyers pay real premiums for updated kitchens, newer systems, and move-in-ready condition. Conversely, deferred maintenance gets priced in aggressively. Square footage and lot Price per square foot averaged $517 across the city, but that figure climbs near the coast and dips inland. Additionally, usable lot space and functional floor plans both add value. Timing and competition With a median of 20 days on market, Oxnard is moving quickly — however, that can shift month to month, which is why current data beats last year’s numbers every time. Taken together, these factors explain why two homes with the same square footage can appraise thousands of dollars apart. For example, a remodeled three-bedroom two blocks from the sand in 93035 lives in a completely different pricing world than a comparable but dated home inland in 93033, even though a search engine may lump them together. Consequently, the most reliable valuations weigh each of these variables against genuinely comparable sales rather than a blanket citywide figure. Zillow vs. Reality: Why Online Estimates Miss the Mark in Oxnard Automated valuation models like the Zestimate are useful for a ballpark, but they struggle in a market as varied as Oxnard. Here is why. First, they lean on public records and past sales that may not reflect your home’s actual condition. Second, they cannot see inside your home — a fully remodeled kitchen and a 1985-original kitchen look identical to an algorithm. Third, and most importantly, they blend ZIP codes and property types together, which we just saw can swing value by six figures. For context, the California Association of REALTORS® publishes statewide median price data, and even those broad figures come with heavy regional caveats. As a result, the most accurate answer to your home’s value almost always comes from a local professional who can walk your home, weigh the comparable sales that truly match it, and adjust for the details a computer cannot see. Average Home Price in Oxnard vs. Your Home’s Real Value Why the average can mislead Average: ~$1,077,690 vs. Median: $802,500 Sellers often search for the average home price
Median Home Price in Ojai, CA (2026): What Real MLS Data Shows
See the real median home price in Ojai, CA for 2026, including current MLS sales data, price trends, days on market, and what the numbers mean for local buyers and sellers.
Ventura County Foreclosures in 2026: A Buyer & Seller Guide
Ventura County foreclosures are rarer than most people think in 2026 — and that changes everything for both buyers and distressed owners. Here’s where to actually find foreclosures for sale, how cash home buyers really price their offers, and the options struggling homeowners have before it’s too late.
San Fernando Valley Real Estate Market Update: July 2026
The San Fernando Valley housing market remained balanced in July 2026, with 516 closed sales, a median price of $947,500, and homes selling at 100% of asking price. See the latest city-by-city prices, days on market, seller concessions, and what the data means for buyers and sellers.
Ventura County Real Estate Market Update: July 2026
Ventura County’s July 2026 housing data is in. See the latest median home price, days on market, sale-to-list ratio, buyer concessions, and a full city-by-city breakdown based on 553 closed MLS sales.
Mountain Fire Rebuild Update: What Ventura County Homeowners & Buyers Need to Know (2026)
Nearly two years after the Mountain Fire, rebuilding in Ventura County is gaining real momentum. Here’s the 2026 status — permit counts, timelines, insurance realities, and what it all means for homeowners and buyers in Somis, Camarillo Heights, and Santa Rosa Valley.
Santa Paula Median Home Price in 2026: What the Latest MLS Data Shows
The Santa Paula median home price in 2026 is holding near $736,000. See the latest MLS data on price trends, market speed, and what buyers and sellers should know.